Platform cash flows, project loans and convertible terms distinguish capital withdrawal from selective financing. A debt-service model traces rates, delivery, power and midterms into the next investment cycle.
OCI offers Rubin and plans to add TPUs. Capital expenditure, customer prepayments and funding targets frame the question of delivery, utilization and cash returns.
New York and Loudoun raise delivery hurdles for some projects. AEP terms show how utility construction liabilities can arise before rent. Carrying cash, delay thresholds and customer exit rights determine returns.
Yandex’s shutdowns and Pay statement separate data integrity, service recovery and compensation. Standby capacity earns a return through customer pricing, reclaimability and demonstrated recovery.
The proposed $7 billion deal remains a reported negotiation. Software value depends on qualified output, maintenance costs and renewal; an Atlas scenario shows how a 30% hourly discount can still raise total cost.
Nebius discloses a multiyear Reflection training and operation agreement. Research inference has a cloud buyer, but contracts, advances, revenue and end-user payment differ; an Atlas scenario tests whole-job output.
Kinwong forecasts a sharp third-quarter profit-margin step-up. Delton’s year-to-date profit is forecast to exceed twice last year’s level, but its implied third quarter falls below Q2. The commercial tests differ: can Kinwong sustain its price–cost spread, and can Delton’s new plants add earnings to a high base?
US AI-related goods imports grew 62% through August, with compute and networking generating almost all net growth. This prioritizes hardware procurement in supply-chain research. Power and cooling opportunities still require orders, qualification and domestic-supply evidence; Chinese companies’ profit shares cannot be read from the import total.
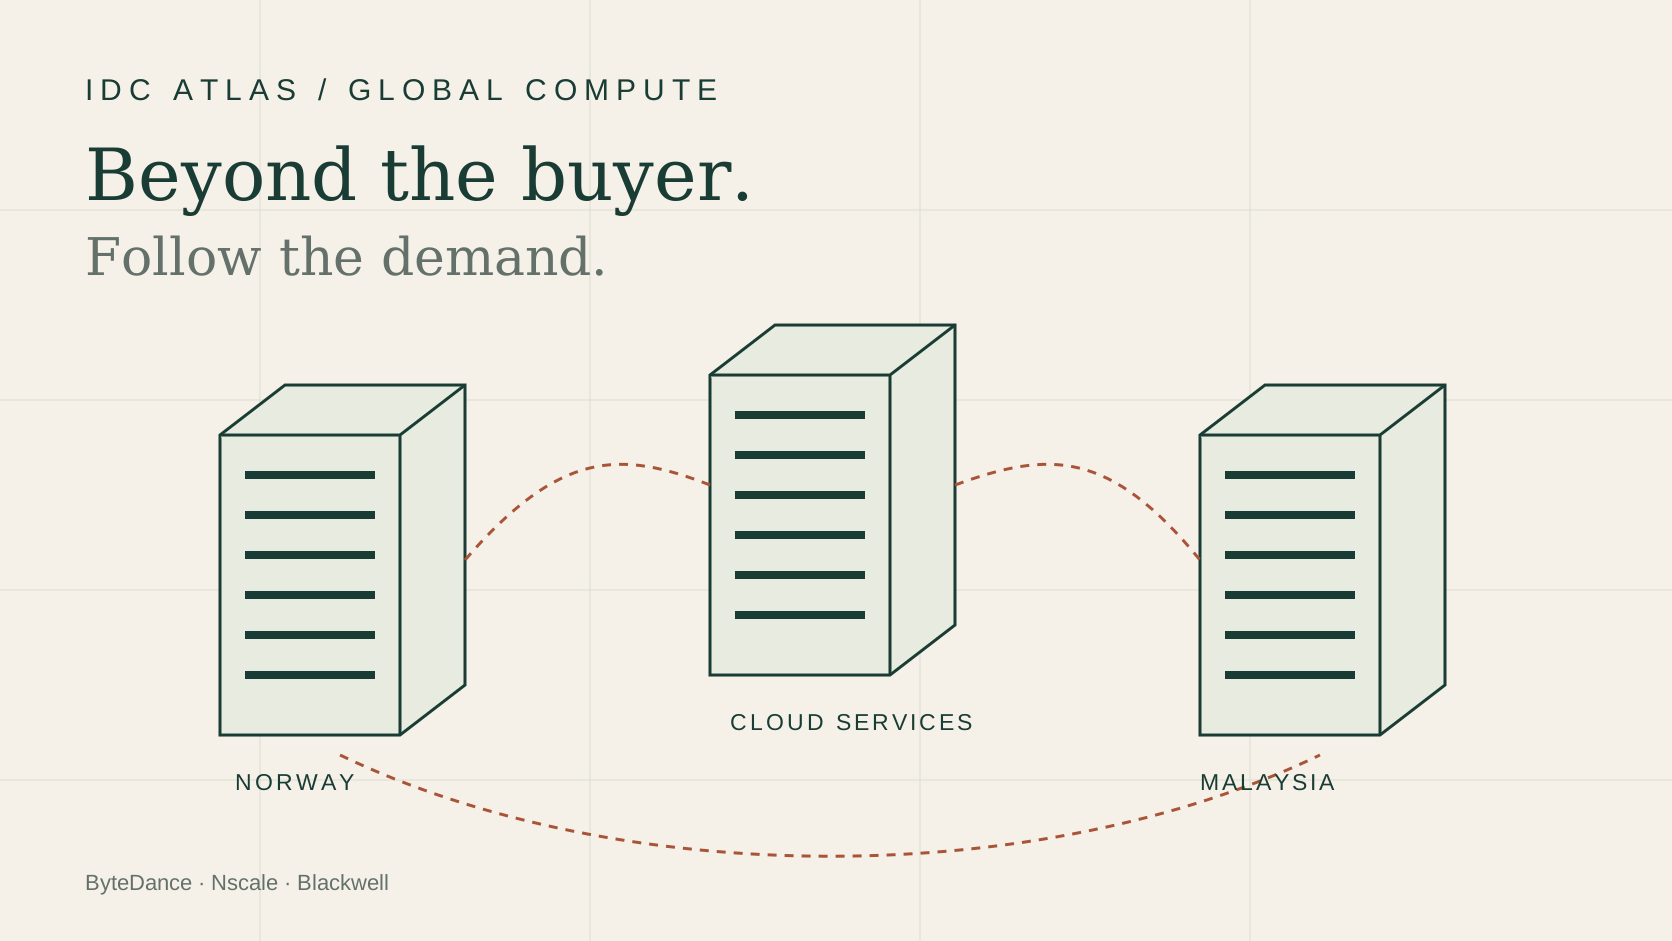
Nscale's filings and reporting on ByteDance reveal how overseas GPU rentals reach equipment suppliers. Delivery, contract terms and operating costs determine the investment implications.
Revenue growth can support a listing. The price shareholders should pay also depends on distribution costs, future funding and the time it takes to earn cash.
NVIDIA’s computing platform remains highly profitable. Slower collections and customer financing are increasing the capital required for growth. The question is whether that support can create durable purchasing power.
Helios expands product content per deployment while adding component, delivery, working-capital and equity costs. Gross-profit dollars must reach shareholders.
Demand supports earnings, but module, component and systems suppliers carry different expansion costs and equity claims. Cash conversion determines how much growth shareholders retain.
LG’s NVIDIA qualification improves its route into AI data-center procurement. Orders, scope of supply and the cash cost of expansion will determine the financial return.
Prosecutors traced a 130-server order. Delivery explains part of supply; reliable operations, capital recovery and lawful sourcing determine its lasting economics.
Purchase-linked warrants align a customer with supplier growth while exposing existing shareholders to dilution. Orders, reusable engineering and product returns determine the bargain.
Credit can help a viable project bridge a funding gap. Without demand and production economics, it may only defer risk. Repayment sources and loss priority matter more than the headline amount.
The platform can influence adoption without owning every model. Hardware choice may preserve trust and expand usage; maintenance costs and paid conversion determine value.
Governance first changes release conditions. Its infrastructure return depends on how those conditions enter purchasing, payment and delivery contracts.
Customer advances support growth but fund future obligations. Revenue, capex and financing need one consistent cash bridge that counts prepayments once.
A more expensive model can deliver cheaper accepted work. Success, review and retries determine unit economics—and whether efficiency expands paid demand.
The reported Anthropic–Lambda agreement lacks key terms. An independent Beacon Point comparison shows how contracts separate compute demand, rent, debt service and equity cash.
Custom silicon can lower customer task costs while expanding supplier profit. Software, components, utilization and cash timing determine who retains the gains.
Routing defaults and deployment convenience influence adoption, without guaranteeing a take rate or new GPU orders. Returns depend on paid conversion, hardware choices and support costs.
Usage is turning into revenue, with Z.ai’s API gross margin reaching 24.6%. Research costs remain much larger than gross profit, separating inference economics from company self-funding.
Partner-owned facilities can reduce upfront spending. Purchase commitments, service liabilities and floating-rate debt determine how much risk stays with Nebius.
Revenue momentum, funding and multiple compute suppliers expand room to grow. Margins, minimum payments and delivery schedules will determine the cash needed to sustain it.
Strong platform sales come with longer customer terms, larger supply commitments and credit support. Revenue, margins, inventory and collections need to be assessed together.
An OpenAI lease, NVIDIA credit support and SB Energy construction link future compute demand to project finance. Returns depend on delivery, payment and the liabilities retained by each participant.
Four provisional 50MW awards create development opportunities. Energy procurement, customer contracts, equipment efficiency and timing will determine the returns.
NVIDIA and financial institutions are broadening access to capital. Draw conditions, ownership and customer cash flows will determine whether projects earn their cost of funding.
Intelligent computing supplied almost half of China Mobile’s computing-services revenue growth. Its effect on group earnings still depends on margins, investment and the trajectory of traditional telecom services.
Volume production reduces one execution risk. Realized prices, qualified shipments, stacking costs and customer system timing determine the cash retained by suppliers.
Batch Zero studies large loads together. Site constraints, upgrade costs, energization dates and acceptable curtailment determine project value—not the queue total.
Model capability, agent runtimes and Claude’s commercial momentum belong to different businesses. Their shared economic question is who retains value as accepted work becomes cheaper.
CoreWeave, Nebius and mining-to-hosting operators sell different services. Equipment ownership, delivery obligations and funding determine how revenue becomes equity cash.
BlackRock-managed funds will own 80% of El Paso, while Meta retains occupancy, construction management and conditional residual-value exposure. The economic question is what Meta pays over the life of the campus.
Volta’s customer commitment and Bitdeer’s lease create cash flows with different durations. IT capacity, rent escalators, a ten-year break and conditional credit support matter more than the headline contract value.
Partners Group plans more than $1 billion of initial equity plus debt to expand AVK into long-term power services. Recurring receipts require asset funding and disciplined allocation of fuel, availability and customer-duration risk.
Reported Nexus financing links construction loans, future bond sales and conditional Google support. Arranging bank capital does not establish that bond buyers have accepted a price or that construction risk has disappeared.
TrendForce expects continued DRAM tightness but possible NAND easing in the second half of 2027. Returns depend on products, delivery and contract terms; “sold out” does not mean industry revenue is secured.
Azure, Google Cloud and AWS reported strong growth, while profit, cash spending and future lease obligations tell different stories. The next test is sustainable cash from added infrastructure, not simply the size of budgets.
Power-generation sales rose 29%, while retail sales to users rose 72%. The measures capture different stages of delivery. Investment returns depend on profitable conversion, cash collection and disciplined factory expansion.
Public procurement can reduce early demand risk, but consortia still fund remaining investment and operations. Sustainability depends on public access commitments, commercial customers and hardware renewal covering the cash requirement.
Broadcom, Apollo and Blackstone are funding custom compute against long-term customer demand. Five-year amortization can reduce dependence on residual value while demanding cash much earlier.
The US ratepayer pledge assigns more incremental generation and grid costs to large customers. Project returns depend on matching minimum payments and power delivery with the arrival of computing workloads.
SpaceX is expanding installed compute while Anthropic plans up to 2GW on AMD’s new platform. Software migration, deployment time and capital tied up before use determine whether a cheaper chip produces a cheaper service.
With 93% revenue growth and a 47% GAAP operating margin, Palantir has demonstrated profitable enterprise AI software. The next test is whether sovereign AI preserves pricing power—and who pays for the additional computing.
AI accounts for 30% of Alibaba Cloud’s external revenue. Qwen’s investment value depends on whether paid use, cloud earnings and infrastructure spending produce sustainable returns.
Azure grew 43%, turning demand into reported revenue. Next quarter’s capital spending of more than $50 billion must now prove itself through deployment speed, cloud margins and cash recovery.
Capability and price tiers can bring more work into production. Revenue, profit and equipment demand may still move differently: paid usage must outgrow both price cuts and efficiency gains.
SK hynix benefits from both higher prices and higher-value products. Long-term agreements and HBM4 improve visibility, while valuation still depends on pricing, yields and expansion returns.
Qualified DRAM output can affect Micron’s prices and share. Equipment suppliers first need executable sales, while GPU vendors need qualified HBM. A listing alone settles none of those outcomes.
Cloud revenue is accelerating, but cash conversion is diverging. AI infrastructure returns depend on the definition of spending, the date capacity becomes usable and the timing of customer payments.
Large leases provide years of revenue visibility. Shareholder returns still depend on construction funding, delivery and the cash left after financing costs.